An Election Rally, the Worst Day Since April 2025, and a Jobs Surprise – All in One Week
By Guardant Wealth Advisors
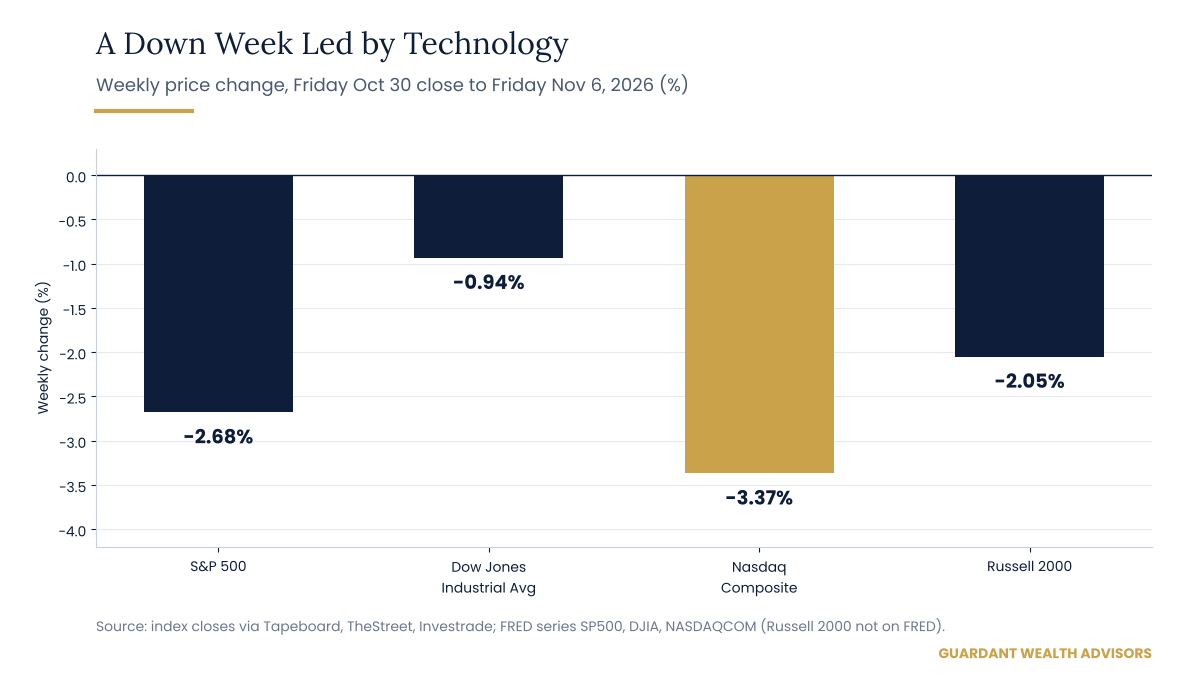
Few weeks pack this much into five trading days. The S&P 500 fell 2.7%, its largest weekly decline since April 2025, while the Nasdaq Composite lost 3.4% for a fourth straight weekly drop and the Dow Jones Industrial Average slipped 0.9%. Behind those totals sat an election, a sharp reversal and an unexpectedly strong labor report.
What We Observed This Week
- Democrats won control of both the House and the Senate in Tuesday’s midterm elections. Markets initially welcomed the clarity, and on Wednesday the S&P 500 rose 1.6%, its best day in three months.
- The mood reversed on Thursday. Investors grew concerned that the new Congress and state officials could restrict new artificial intelligence (AI) data centers, and semiconductor stocks led a broad selloff. The S&P 500 fell 4.4%, the Dow lost more than 1,800 points and the Nasdaq dropped 5.5%, leaving that index more than 10% below its October record. For the broad market, it was the worst day since April 2025.
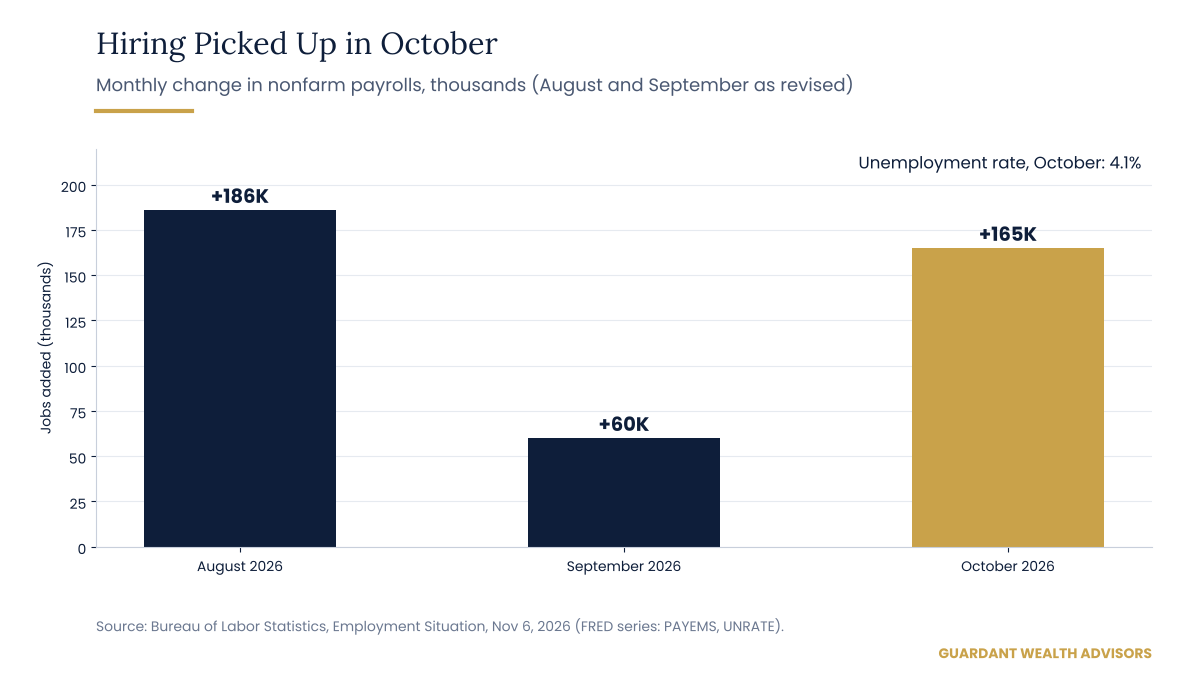
- The labor market surprised to the upside. Employers added 165,000 jobs in October, well above the consensus forecast of 59,000, and the unemployment rate dipped to 4.1%. Revisions added a combined 84,000 jobs to August and September.
- Manufacturing held up. The Institute for Supply Management (ISM) manufacturing index rose to 55.5 in October, with production at its highest level since November 2021.
- Oil fell sharply. Brent crude settled at $98.32 a barrel on Friday, down about 13% for the week, as investors weighed the chance of a U.S.-Iran peace agreement.
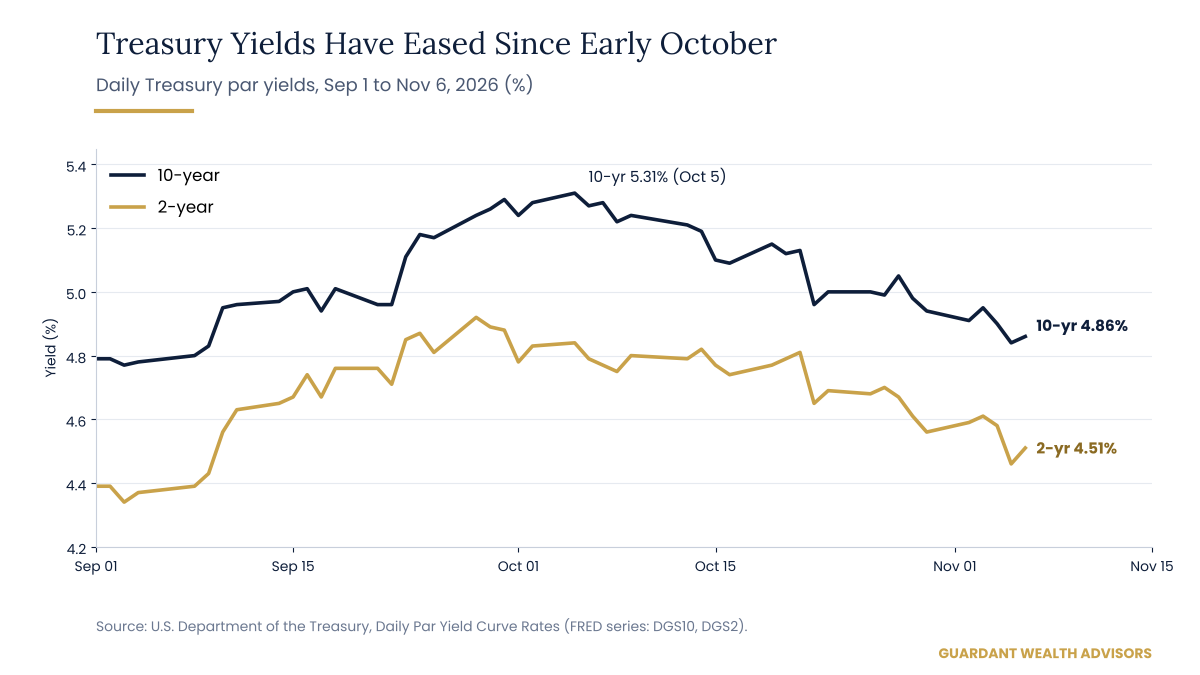
- Bonds rallied. The 10-year Treasury yield ended the week at 4.86%, down from 4.94%.
What We Are Watching
- The Federal Reserve’s December 8-9 meeting. After the jobs report, futures priced a 76.8% chance of a quarter-point hike, up from 66.9% a day earlier, according to CME FedWatch data on November 6.
- The October Consumer Price Index (CPI) on Tuesday, November 10, which will show whether the recent drop in oil prices is beginning to reach consumers.
- How the incoming Congress approaches AI infrastructure and energy policy. Campaign positions do not always become legislation, and details may take months to emerge.
- Whether Friday’s partial rebound in technology shares holds.
The Long-Term Takeaway
This week was a reminder that markets often react first and reassess later. A political outcome moved stocks up 1.6% one day and down 4.4% the next, while the underlying economy produced one of its strongest jobs reports in months. We believe investors are generally better served by separating short-term reactions to headlines from the longer-term drivers of returns, such as earnings, interest rates and economic growth, and by holding a diversified portfolio built to withstand weeks like this one.
This content is for educational purposes only and does not constitute personalized investment advice or a recommendation to buy or sell any security. The information provided reflects general market commentary based on publicly available information and is not tailored to the financial situation of any individual. Investing involves risk, including the possible loss of principal. Past market performance is not indicative of future results. Guardant Wealth Advisors, LLC is a registered investment adviser. Registration does not imply a certain level of skill or training.
Weekly Market Commentary: November 2 – 6, 2026
An Election Rally, the Worst Day Since April 2025, and a Jobs Surprise – All in One Week
By Guardant Wealth Advisors
Few weeks pack this much into five trading days. The S&P 500 fell 2.7%, its largest weekly decline since April 2025, while the Nasdaq Composite lost 3.4% for a fourth straight weekly drop and the Dow Jones Industrial Average slipped 0.9%. Behind those totals sat an election, a sharp reversal and an unexpectedly strong labor report.
What We Observed This Week
What We Are Watching
The Long-Term Takeaway
This week was a reminder that markets often react first and reassess later. A political outcome moved stocks up 1.6% one day and down 4.4% the next, while the underlying economy produced one of its strongest jobs reports in months. We believe investors are generally better served by separating short-term reactions to headlines from the longer-term drivers of returns, such as earnings, interest rates and economic growth, and by holding a diversified portfolio built to withstand weeks like this one.
This content is for educational purposes only and does not constitute personalized investment advice or a recommendation to buy or sell any security. The information provided reflects general market commentary based on publicly available information and is not tailored to the financial situation of any individual. Investing involves risk, including the possible loss of principal. Past market performance is not indicative of future results. Guardant Wealth Advisors, LLC is a registered investment adviser. Registration does not imply a certain level of skill or training.
more posts:
Weekly Market Commentary: October 19 – 23, 2026
Student of the Market: October 2026
Weekly Market Commentary: October 12 – 16, 2026